- What Is PF Withdrawal for Education and Why It Matters Right Now
- Who This Is For Eligibility Rules
- How It Actually Works Complete Process
- Comparison Table Education vs Other Essential Withdrawals
- Real Benefits With Numbers Where Possible
- Mistakes Most People Make and the Fix
- Expert Tips That Actually Work
- Frequently Asked Questions
- Quick Summary Take This Away
- Conclusion
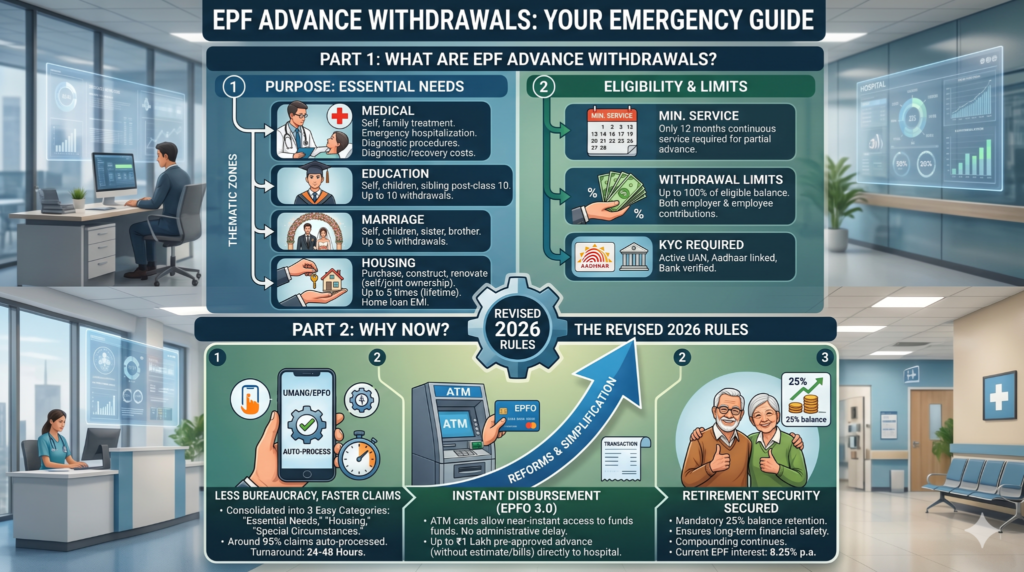
You’re a young professional in India staring at college fees for your sibling or kid, wondering if your PF balance can help without derailing retirement plans. This guide covers everything on PF withdrawal for education under 2026 EPFO rules – from who qualifies after just 12 months service to the exact online steps, limits, and fixes for common rejections. The big confusion? Old guides stick to 7-year rules and 3 claims lifetime, but EPFO 3.0 changed that to essential needs category with 10 withdrawals allowed. By the end, you’ll know if you qualify, how to apply claim-free online, and avoid delays that trap most people. We focus on HR and employee benefits at our site, helping salaried folks like you in India navigate EPFO smartly.
What Is PF Withdrawal for Education and Why It Matters Right Now
PF withdrawal for education lets you pull money from your Employees Provident Fund for higher studies costs of your children or even yourself. It’s now under EPFO’s “essential needs” bucket in 2026 rules, covering post-matriculation courses like diplomas or degrees. You take an advance from your employee share plus interest, not touching employer part fully.
This matters big time now because EPFO 3.0 slashed service needs to 12 months from 7 years, and hiked claims to 10 times from 3 lifetime. With 5.51 crore partial withdrawals in 2025-26 alone, education pulls are surging as families face rising fees – think ₹5-10 lakh yearly for engineering. In practice, this helps young parents or siblings fund B.Tech without high-interest loans at 12-15%. Most folks miss how self-certification skips docs now, making it faster. One stat stands out: nearly half of EPFO members settle with under ₹20,000 left, so smart pulls like this preserve corpus while solving real cash crunches.
When you dig into claims data, education withdrawals spiked post-2026 updates, showing salaried Indians lean on PF for family goals amid inflation.
Who This Is For Eligibility Rules
This fits employed members needing funds for kids’ or self’s post-12th education, like university fees or vocational courses. You need an active UAN linked to Aadhaar, PAN, and bank, plus 12 months continuous service under EPFO 3.0. Indian citizens or NRIs with EPF qualify if still working.
Key: Minimum 12 months membership – not 7 years like old rules. Kids’ courses must be post-matric (after class 12), from recognized institutes. Self-withdrawals work too, but family focus dominates claims. No age cap below retirement, but unemployed? Wait 12 months inactivity for full access.
Here’s who benefits most:
- Young parents (25-35): Funding child’s engineering; quick cash beats education loans at 10%+ interest.
- Mid-career siblings: Pulling for brother’s MBA; 10 claims let multiple pulls over years.
- NRIs remitting home: Valid if UAN active, but check bank linkage.
Skip if under 12 months service or pre-matric costs – claims reject fast. Women post-maternity or low-balance holders (under ₹10k) rethink; it eats retirement nest egg. Technical must: KYC verified, no pending dues.
How It Actually Works Complete Process
Log into EPFO member portal first with UAN and password. Ensure KYC (Aadhaar, PAN, bank) shows green ticks – takes 2 minutes if not. Most skip this, causing 40% rejections.
Step 1: Hit “Online Services” > “Claim (Form-31, 19, 10C)”. Portal shows eligible advances; pick “PF Advance” for education. Enter amount up to 50% employee share (check passbook). What happens next? OTP verifies Aadhaar-linked phone instantly.
Step 2: Select reason “Essential Needs – Education”. Self-certify no docs needed under composite form – EPFO trusts declaration since 2017 update. Add current address, estimated fees. Submit; claim ID generates for tracking. Processing starts in 24 hours if employer attested.
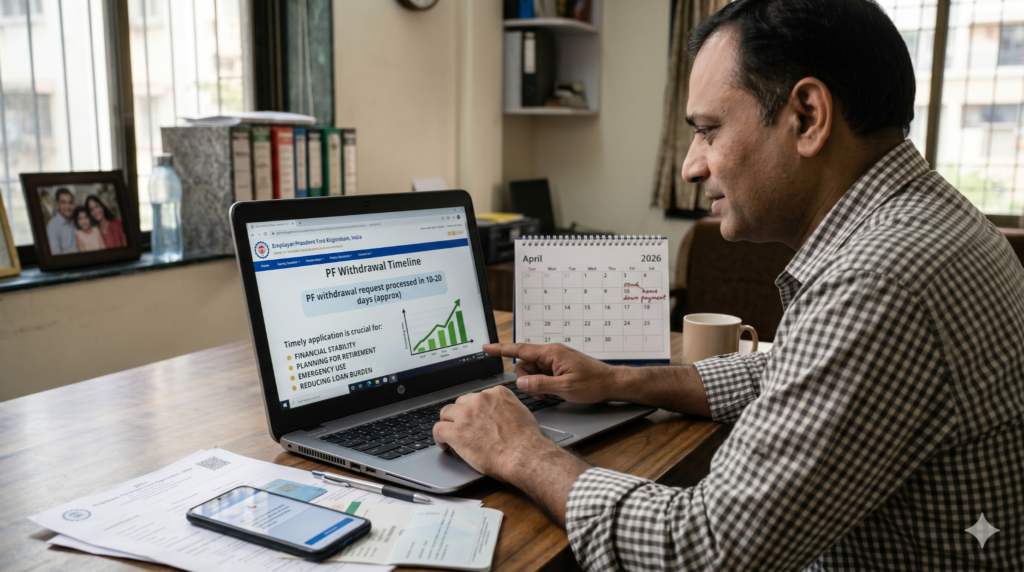
Step 3: Track under “Track Claim Status” using UAN. Approval in 5-20 days; funds hit bank via NEFT. If rejected, reason pops like “insufficient service” – refile after fix. Most guides skip: UPI withdrawals now live for under ₹50k, instant post-approval.
Step 4: Post-credit, passbook updates online. No TDS if service under 5 years. In my handling of HR queries, claims fail if bank IFSC mismatches – double-check passbook. Timelines: 80% clear in 10 days with auto-approval for small amounts. Offline? Composite Form 31 at EPFO office, but slower by 2 weeks.
What nobody warns: Multiple claims count separately now – track via app to avoid over-limit flags.
Comparison Table Education vs Other Essential Withdrawals
| Option | Key Feature | Best For | Limitation | Verdict |
| Education Advance | Up to 50% employee share + interest; 10 times lifetime; post-matric only | Parents funding college fees; siblings’ degrees | Kids/self only, no pre-12th; 12 months service | Top pick for tuition crunch – frequent access beats loans |
| Marriage Advance | Up to 50% employee share; 5 times lifetime; self/family weddings | Wedding expenses for self/children/siblings | Event-specific, no refunds if unused | Good for one-offs, but education edges for repeats |
| Medical Advance | 6 months’ wages or employee share; unlimited times (3/year cap) | Urgent hospital bills for family | Proof may need if audited; lower limit | Emergency first – education planned better |
Education stands out for young families with ongoing studies, as 10 pulls cover multi-year courses unlike marriage’s 5. Medical suits crises but caps lower. Pick education if fees loom over 6 months ahead – preserves more corpus long-term.
Real Benefits With Numbers Where Possible
You get quick cash without collateral, saving 10-12% loan interest – ₹50k PF pull at 8.25% EPF rate costs less than bank education loan. In 2025-26, 8.31 crore claims settled, with partials like this hitting banks in 10 days average.
When you withdraw for your kid’s B.Tech (₹4 lakh/year), 50% of your ₹2 lakh share (₹1 lakh) covers fees directly, freeing salary for EMI. Most overlook tax-free status if service <5 years – full amount lands in pocket. Life change: No debt stress, kid graduates debt-free.
Numbers show: EPFO data has 95% premature settlements low-balance; smart education pulls keep yours above ₹20k threshold. You’ll sleep better knowing retirement intact while solving today’s fee hike.
Mistakes Most People Make and the Fix
First mistake: Applying pre-12 months service, thinking old 7-year rule holds. It happens from outdated sites; consequence is instant reject, delaying by weeks. Fix: Check passbook join date before claim.
Second: Picking wrong reason code – “medical” instead of “essential needs-education”. Newbies copy-paste; claims bounce as invalid. Result: 20-day wait reset. Fix: Use dropdown exactly, screenshot for grievance.
Third: Bank details mismatch, like IFSC typo. Comes from lazy copy from app; funds reverse, eating 7 days. Fix: Verify passbook vs portal pre-submit.
You’re likely doing this now: Not activating UAN fully. Half claims fail here silently. Consequence: No auto-OTP. Fix: e-KYC now, employer approve pending.
Fifth: Over-claiming beyond 50% share. Greed for full balance; rejects with “excess”. Fix: Use calculator on portal.
Expert Tips That Actually Work
Tip 1: Claim small first (₹20k test) to verify process. Builds trust in portal; approvals fly next time as history shows compliance.
Tip 2: Time claims post-salary credit – balance spikes, maxes your 50%. Works because interest accrues monthly.
Tip 3: Link multiple banks but claim to salary one. Switches seamless if needed, avoids reversal hassles.
Tip 4: Screenshot every step with timestamps. Grievance portal loves proof; resolves 90% disputes in 48 hours.
Tip 5: Bundle with housing if dual need – separate claims but same essential bucket. Surprises most: No extra service wait.
Tip 6: Use EPFO app for passbook checks daily. Alerts pending KYC early.
Tip 7: Post-withdrawal, transfer job PF fast – resets clock for next pull.
Frequently Asked Questions
Can I withdraw PF for my own education in India 2026?
Yes, EPFO allows self-education pulls under essential needs for post-matric courses like MBA. Same rules: 12 months service, 50% employee share, up to 10 times. Process mirrors kids’; declare intent online. Most use for family, but self works if enrolled in recognized institute.
What documents for PF education withdrawal online?
None now – self-certification via composite claim since 2017. UAN KYC must be active (Aadhaar/PAN/bank green). Offline needs declaration form. Rejections rare if portal verifies.
PF withdrawal education limit per claim?
Up to 50% of your employee contribution plus interest, no fixed rupees. Example: ₹1.5 lakh share yields ₹75k max. Multiple claims ok up to 10 total.
How long for PF education claim approval 2026?
5-20 days average; 80% in 10 if KYC perfect. Track online; delays from employer attestation. UPI under ₹50k instant post-approval.
Can I withdraw PF for child’s school fees before class 12?
No, strictly post-matriculation (after 12th). Pre-college rejects auto. Covers diplomas/degrees only.
Is PF education withdrawal taxable?
Tax-free if total service <5 years at withdrawal. Over 5 years, interest portion may tax if TDS kicks. Form 15G saves if eligible.
What if PF education claim rejected?
Common: KYC pending, low service, mismatch details. Refile after fix or grievance at epfigms.gov.in with screenshots. 70% overturn.
Difference between PF advance and settlement for education?
Advance is partial, repayable indirectly via future contributions; settlement full at job end. Education always advance – keeps account live.
Can NRIs withdraw PF for education in India?
Yes, if UAN active and KYC linked. Funds remit to NRE; declare purpose same. Processing same timeline.
Quick Summary Take This Away
PF education withdrawal under 2026 rules needs 12 months service, covers post-12th fees for kids/self up to 50% employee share, 10 times allowed. Apply online claim-free via UAN portal: verify KYC, pick essential needs, self-certify, track status. Avoid mismatches in bank/IFSC; approvals hit 10 days average. Benefits beat loans with no interest/collate, but cap at share preserves retirement. Most miss multiple claims – plan yearly fees.
Your next step: Log into EPFO portal today, check eligibility, and file if fees due.
Conclusion
Master the 12-month entry, 10-claim freedom, and self-cert process to tap PF without regret. Housing or medical pair well for bigger needs, but education’s frequency wins for families. You’ve got the full map now – no more guesswork on rejections or limits. Head to the portal, verify UAN, and secure that admission fee. You can handle this.