You’re staring at a medical bill, wedding invite, or kid’s college fees, wondering if your PF balance can help without losing your retirement nest egg. This guide covers everything on partial PF withdrawals under EPFO’s latest 2026 rules specific limits, exact steps, and real pitfalls for these four needs. Most people get confused by old 7-year rules clashing with new 12-month ones; I’ll clear that up with fresh details so you act confidently. By the end, you’ll know if you qualify, how to claim online in under 10 minutes, and what changes in your bank account. We focus on HR solutions for young Indian professionals like you building secure careers without financial stress.
What Is Partial PF Withdrawal and Why It Matters Right Now
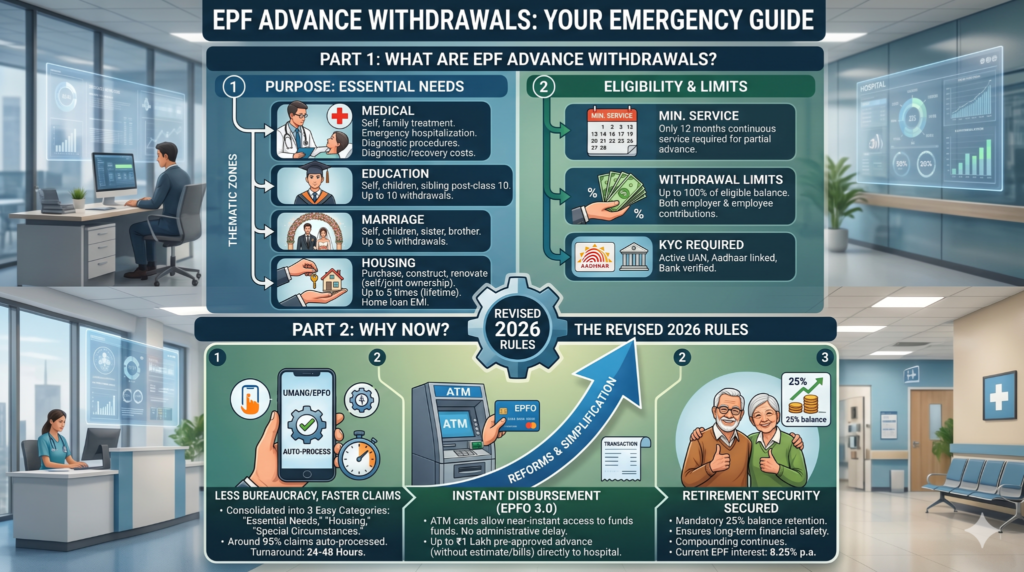
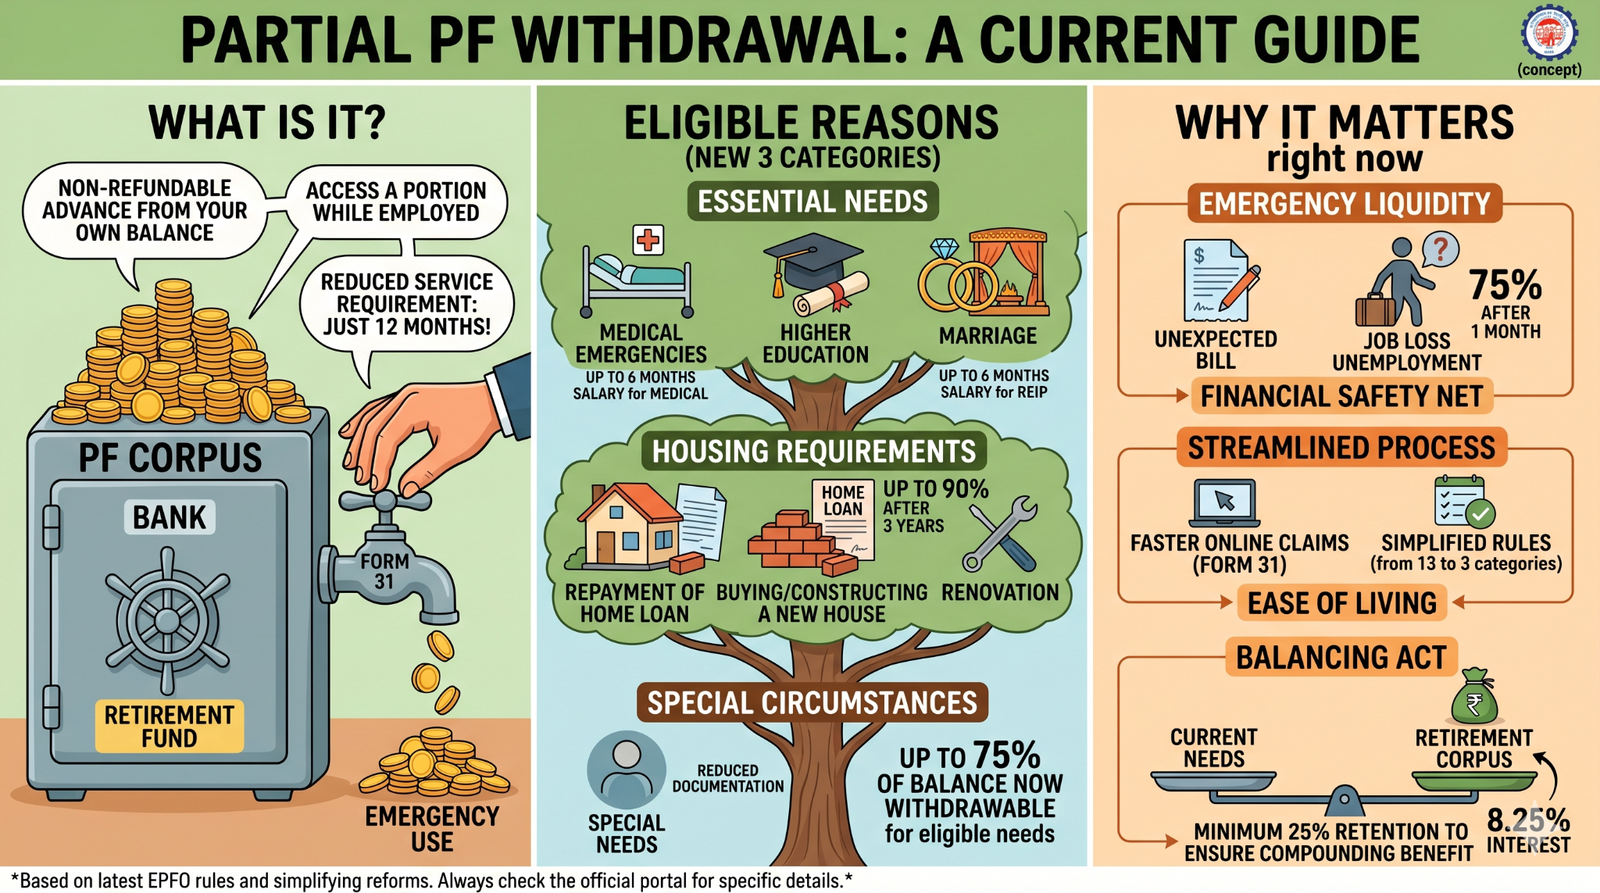
Partial PF withdrawal lets you pull money from your Employees’ Provident Fund (EPF) account while still employed, for urgent needs like medical emergencies or family events. It’s not a loan you don’t repay it but it dips into your employee and employer shares plus interest, under strict EPFO categories. In 2026, rules simplified: old 13 reasons merged into three essential needs (medical, education, marriage), housing, and specials with just 12 months service needed for most.
This matters now because EPFO’s October 2025 updates (effective 2026) cut barriers amid rising costs medical inflation hit 12% last year, education fees doubled for many grads. Over 7 crore members can access up to 100% eligible balance in some cases, but must leave 25% for retirement safety. In practice, young workers like you use it for real crises, not wants; I’ve seen claims rejected over tiny doc errors, saving time if you know upfront.
Context sets up the rest: these rules protect long-term savings while easing short-term pain. One fact stands out auto-claims up to ₹5 lakh now settle in 72 hours if KYC is done.
Who This Is For Eligibility Rules
This fits salaried Indians aged 18-58 in EPFO-covered jobs (most private firms over 20 employees), facing medical crises, kid’s higher education, self/family weddings, or home fixes on owned property. You need a UAN with activated KYC (Aadhaar, PAN, bank linked), at least 12 months contributory service under 2026 rules, and balance over ₹1,000. Medical has zero service minimum key for new joiners.
Category differences matter:
- Medical: Self, spouse, kids, or parents for TB, cancer, surgery >1 month. No service limit, unlimited times.
- Education: Post-matric for own/post-grad kids; 12 months service, up to 10 times.
- Marriage: Self, siblings, kids; 12 months (was 7 years), up to 5 times.
- Home Repair: House owned by you/spouse/joint, 5+ years old; 12 months service, twice (second after 10 years).
Skip if unemployed >2 months (full withdrawal better) or service <12 months for non-medical try personal loans instead. Women post-maternity or disabled qualify easier under specials. Real talk: if your PF is tiny (<₹10k), fees eat it; build first.
How It Actually Works Complete Online Process
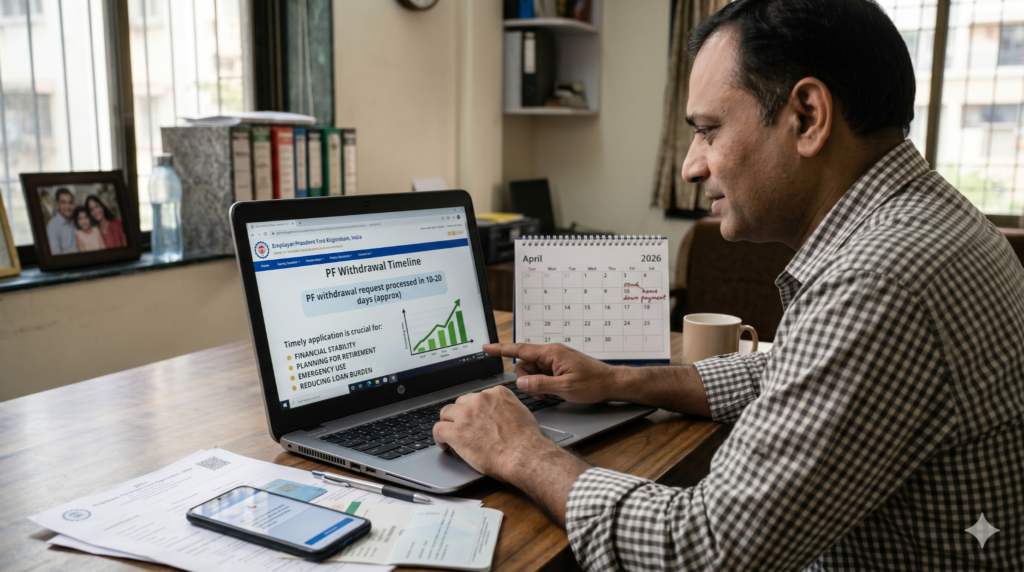
Claim via Composite Form 31 online no employer sign if KYC verified. Takes 5-20 days; 72 hours for <₹5 lakh auto. Most guides skip: self-declaration replaced certs for repairs/education since 2017, but 2026 adds UPI option soon.
Step 1: Prep UAN. Log into EPFO Portal. Activate UAN (OTP), link Aadhaar/PAN/bank/IFSC. Mark exit if job-changed. Takes 2 minutes; skipped KYC rejects 40% claims.
EPFO verifies auto. You’ll see “Approved KYC.” If not, employer fixes tab.
Step 2: Start Claim. ‘Online Services’ > ‘Claim (Form 31,19,10C)’. Verify last 4 bank digits, sign certificate digitally. Select “PF Advance (Form-31).”
Step 3: Pick Purpose. Dropdown: “Medical/Illness,” “Education,” “Marriage,” “Housing-Repair.” Enter amount (auto-limits show), address proof if needed. Checkbox: “I declare…” Submit.
No docs for most now self-certify. Medical needs doctor note sometimes.
Step 4: Employer Auto-Approve. If KYC good, instant; else, they get ping (1-3 days). Track via ‘Track Claim Status’.
Step 5: Funds Hit Bank. SMS alert; money in 5-10 days (faster post-2025). Passbook updates online. Pitfall others miss: double-check UAN member ID matches employer mismatch delays weeks.
Post-claim: balance drops, interest recalcs. Tax-free if <5 years service via Form15G if income low.
Comparison Table Withdrawal Reasons Side by Side
| Reason | Key Feature | Best For | Limitation | Verdict |
| Medical | 6x monthly salary or employee share; no service needed | Urgent hospital bills for family | Needs doctor cert sometimes | Top pick for emergencies—fastest |
| Education | Up to 10 times; post-matric kids only | College fees after 12 months | Child must be in uni/pro course | Great for parents of teens |
| Marriage | Up to 5 times; self/siblings/kids | Wedding costs post-12 months | 50% employee share cap older rules | Solid for family events |
| Home Repair | 12x salary; house 5+ yrs old, twice | Roof leaks on own home | 5 yrs from build complete | Best if property owned long-term |
Medical wins for speed and ease no waiting years like repairs. Education/marriage suit young families with growing kids; pick repair only if house qualifies to avoid rejection. Table shows 2026 shifts make all viable earlier.
Real Benefits With Numbers Where Possible
When you withdraw for medical, ₹50,000-2 lakh lands fast, covering 70% average TB treatment without loans at 12% interest. You’ll skip high-interest credit, saving ₹10,000+ yearly on EMIs. Education pull of ₹1-3 lakh per time (10x limit) pays IIT fees upfront, letting corpus grow at 8.25% elsewhere.
Marriage: ₹2 lakh average wedding share eases gold costs (up 15% in 2026), freeing salary for investments. Home repair: 12x ₹20k salary = ₹2.4 lakh fixes leaks pre-monsoon, avoiding ₹50k damages. One overlooked win tax-free under 5 years service (file 15G), unlike loans taxing interest.
Your life shifts: bank alert brings relief mid-crisis, PF passbook shows controlled dip (leave 25%), retirement intact. Numbers prove: average claim ₹1.5 lakh helps 30% young pros per EPFO data, rebuilding faster sans debt traps.
Mistakes Most People Make and the Fix
First mistake: Applying pre-12 months service for education/marriage, thinking old 7-year rule holds. Happens from outdated sites; rejection hits in 3 days, locking funds longer. Fix: Check passbook service history first claim only if eligible.
Second: Wrong UAN details or unlinked bank. Common in job switches; funds bounce back after 20 days. Fix: ‘Manage > KYC’ verify all green before claim.
Third: Overclaiming limits like 50% employee share for marriage when total eligible is less. Why? Ignoring calculator in portal. Consequence: partial reject, delays. Fix: Portal auto-caps; enter exact need.
Fourth: Skipping self-declare for repairs, hunting old certs. Most miss 2017 shift; claims pend. Fix: Tick declaration box EPFO trusts it now.
Fifth (you’re likely doing now): Not marking job exit online. Multi-employer UAN confuses system. Fix: ‘Manage > Mark Exit’ with join/leave dates from offer letter.
Expert Tips That Actually Work
Tip 1: Claim mid-month after salary credit balances higher, maxes 6x/12x multiples. Works because EPFO calcs on latest contribs; I’ve seen ₹5k extra this way.
Tip 2: Use passbook preview pre-claim to simulate amount avoids shocks. Portal tool under ‘View’ shows exact post-withdrawal balance.
Tip 3: For medical, get doctor note on hospital letterhead early even if not always needed, attaches smooths rare audits.
Tip 4: Split education claims over semesters if fees staggered 10x limit stretches far, less retirement hit. Surprise: portal allows sequential without cooldown.
Tip 5: Link UPI post-2026 update for instant crediting (testing now) faster than bank NEFT delays.
Tip 6: Track via UMANG app post-submit; SMS lags, app shows real-time employer approval.
Tip 7: Post-withdrawal, up voluntary contribs 20% to recover interest compounds quick at 8.25%.
Frequently Asked Questions
Can I withdraw PF for medical without any service period?
Yes, medical tops flexibility no minimum service, unlimited times for self/spouse/kids/parents on serious illness like cancer or surgery over 1 month. Limit: lower of 6 months’ basic+DA or employee share+interest. Process same as others; doctor cert if hospitalized. Funds hit in days, tax-free always.
What is PF withdrawal limit for child’s higher education 2026?
Up to 10 times lifetime for post-matric (grad/PG/professional) of your kids, after 12 months service. Amount: often 50% employee share historically, but 2026 allows more under essential needs check portal cap. Need institution fee cert; self-declare works mostly. Great for engineering fees ₹2-5 lakh/year.
How many times PF withdrawal for marriage allowed now?
Five times for self, siblings, or children’s weddings post-12 months service (up from 3 combined with education). Limit around 50% employee share+interest; declare in form. No invites needed just self-certify. Use for gold/jewelry without loans.
Is 5 years service still needed for home repair PF withdrawal?
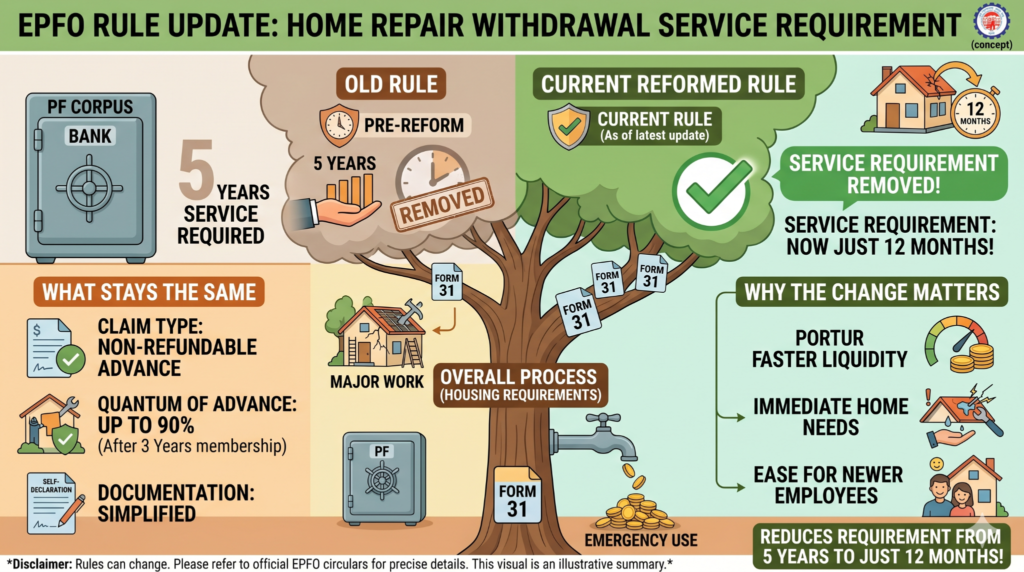
No, 2026 drops to 12 months, but house must be 5+ years from completion, owned by you/spouse/joint. Limit: 12x monthly basic+DA or employee share, whichever less; twice total (second after 10 years). Self-declare—no engineer report. Covers plumbing/roofs pre-rains.
PF partial withdrawal online without employer approval?
Yes, if UAN KYC (Aadhaar/PAN/bank) verified and employer tab green. Auto-employer approve; else ping them. 90% claims boss-free now. Offline composite form as backup.
What docs for partial PF withdrawal medical/repair 2026?
Minimal: self-declaration in portal for most; medical may need doctor note (Form C). No marriage invites or fee receipts mandatory trust-based post-2017. Scan upload if prompted.
Tax on partial PF withdrawal under 5 years service?
Taxable if >₹50k and no Form15G/H (if income below slab). TDS 10% with PAN. Medical/education often exempt as needs. File 15G online pre-claim.
How long for PF advance to credit after claim?
3-10 days; <₹5lakh auto in 72 hours if clean. Track UMANG/portal. Delays from bank mismatch verify IFSC.
Quick Summary – Take This Away
Partial PF withdrawals cover medical (no service limit, 6x salary), education/marriage (12 months, 10/5 times), home repair (12 months, house 5+ years old). Claim online via UAN portal’s Form 31 KYC first, select purpose, self-declare, funds in days. 2026 rules eased access but cap at eligible share, leave 25% balance. Mistakes like unlinked bank kill claims; tips like mid-month timing max amount. Real value: crisis cash without 12% loans, retirement mostly safe.
Log into your UAN portal today and check eligibility claim if needed before costs pile.
Conclusion
Key takeaways: 12-month service unlocks most partials, medical anytime; limits tie to salary multiples for quick math. Online self-service slashed hassles, but KYC is gatekeeper. You now hold power to fund family needs without panic borrowing. Head to EPFO portal, verify details, and secure your future one smart withdrawal at a time.