- What Is PF Withdrawal After Resignation and Why It Matters Right Now
- Who This Is For
- How It Actually Works Complete Process
- Comparison Table PF Withdrawal Options Side by Side
- Real Benefits With Numbers Where Possible
- Mistakes Most People Make and the Fix
- Expert Tips That Actually Work
- Frequently Asked Questions
- Quick Summary Take This Away
- Conclusion
You just resigned from your job and now need your PF money fast. This guide covers the exact EPFO rules for PF withdrawal after resignation in India, including the waiting period, full online process, tax rules, and common pitfalls. By the end, you will know if you qualify, how to claim step by step, and what to do if it gets stuck.
The confusing part is the waiting period often 1 month for 75% and 2 months for full withdrawal under 2026 rules. We clear that up here with specifics. This site helps young Indian professionals like you with HR topics: PF, gratuity, job switches, and more. No fluff, just what works.
What Is PF Withdrawal After Resignation and Why It Matters Right Now
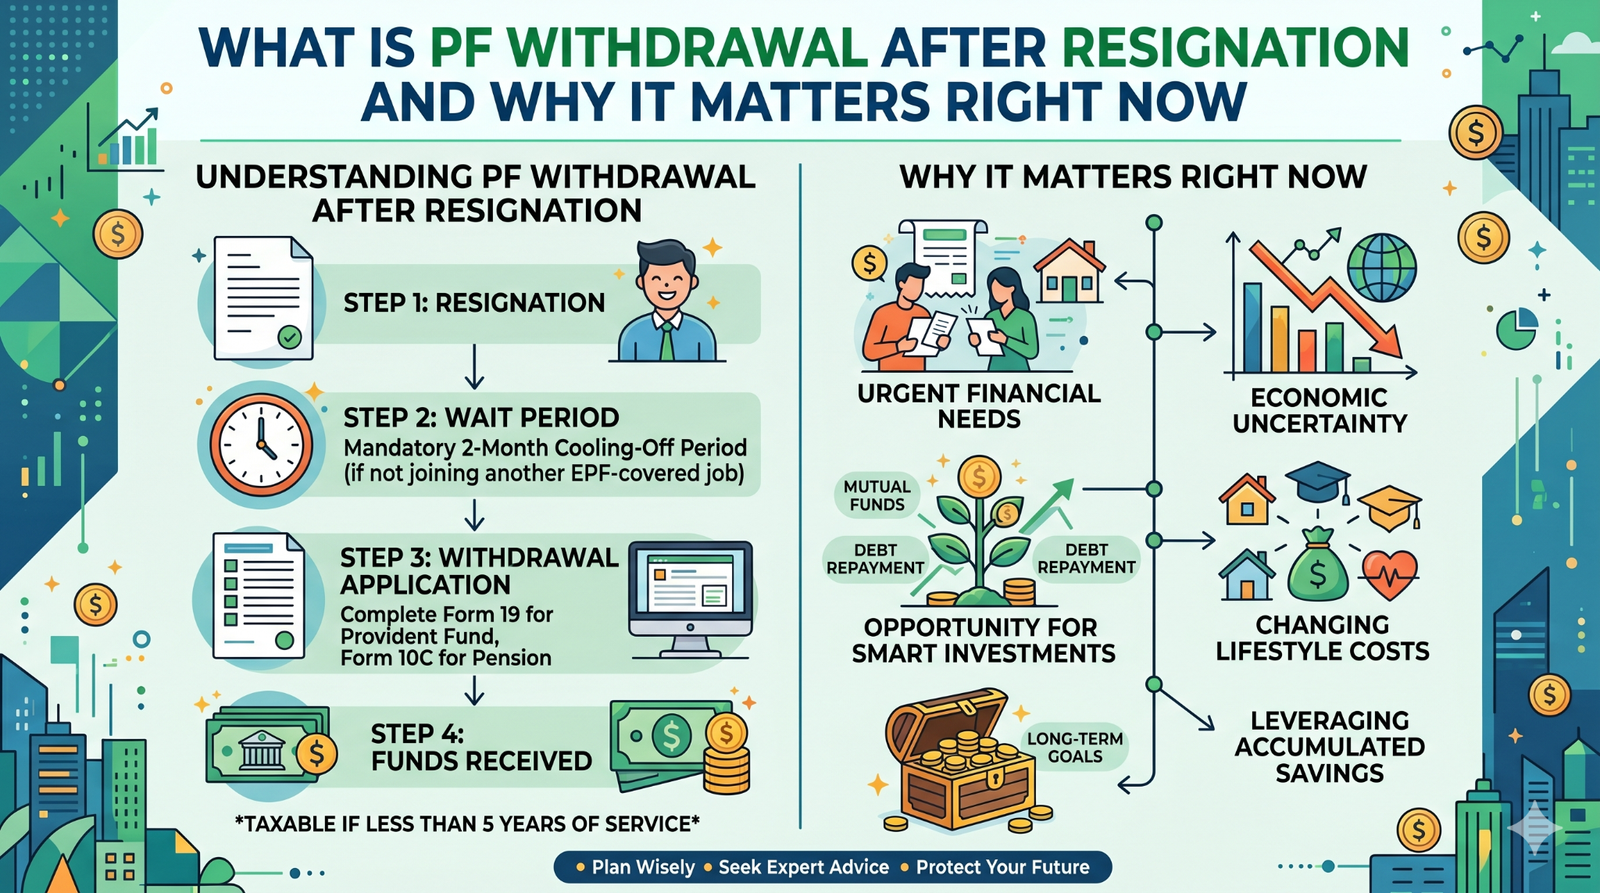
PF withdrawal after resignation means claiming your full Provident Fund balance from EPFO after you leave a job. This includes your contributions, your employer’s share, and all interest earned.
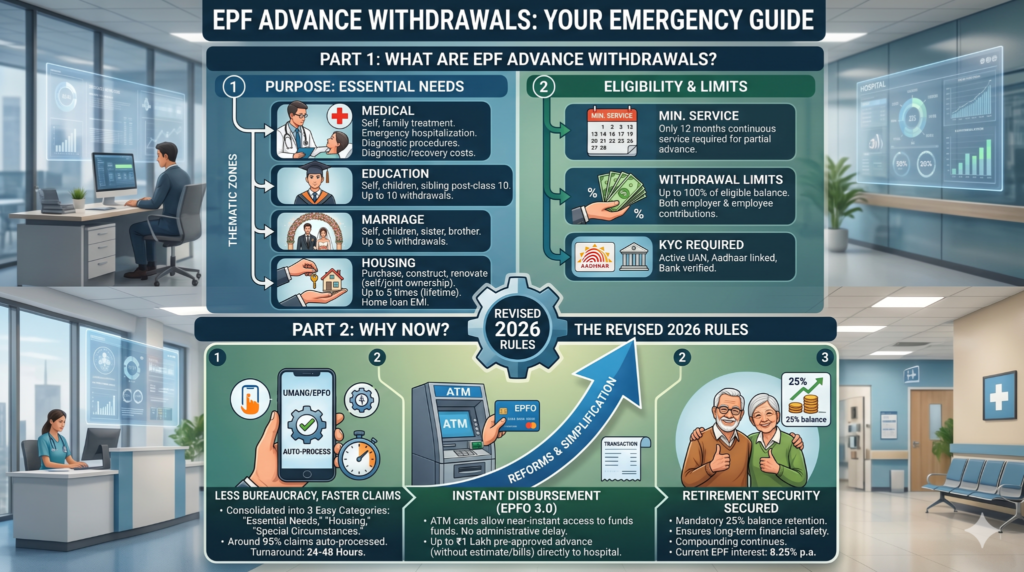
It matters because job switches are common for 18- to 25-year-olds in India. EPFO data shows over 7 crore subscribers, and claims settle faster in 2026 thanks to EPF 3.0 updates. Right now, with layoffs and switches rising, getting your PF quick helps cover rent or bridge to your next gig.
The niche angle: many guides ignore the split withdrawal 75% after 1 month unemployed, rest after 2 months or 12 months in some cases. That is key for planning cash flow.
In practice, this process lets you access retirement savings early without penalties if rules are met. Most young people use it for emergencies, not retirement.
Who This Is For
This applies to salaried employees under EPFO who resigned or lost their job. You need at least 1-2 months unemployment to start.
Key requirements:
- Active UAN linked to Aadhaar, PAN, and bank account.
- Employer must mark your exit in EPFO portal.
- KYC verified on unifiedportal-mem.epfindia.gov.in.
You must be unemployed for 1 month minimum for partial (75%) claim.
Category differences:
- Under 5 years service: Full withdrawal ok, but tax if over Rs 50,000.
- Over 5 years: Tax-free if continuous service.
- With EPS (pension): Use composite claim for PF + pension withdrawal.
Not for you if already joined new job transfer instead. Or if service under 2 months at last employer.
Young job-hoppers qualify easiest, but check exit date first.
How It Actually Works Complete Process
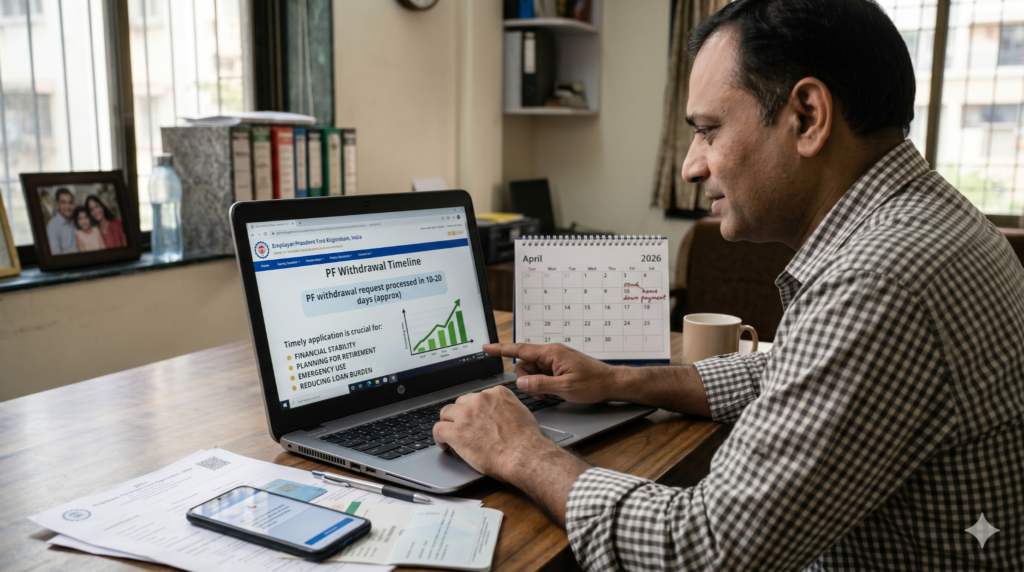
The process uses the EPFO Unified Member Portal. Most claims settle in 7-15 days if KYC is done.
Step 1: Verify details. Log into EPFO Portal with UAN and password. Check Aadhaar, PAN, bank linked under “Manage” tab. If not, e-sign with Aadhaar OTP. Takes 5 minutes.
Step 2: Confirm exit. Employer updates your date of exit (DOE). Wait for that usually 7-10 days post-resignation. You see it under “Service History.”
Step 3: Wait the period. After DOE +1 month unemployed, eligible for 75% via Form 19. After +2 months, full 100%.
Step 4: File claim. Click “Online Services” > “Claim (Form-31, 19, 10C & 10D)”. Select “PF Final Settlement” for full. Auto-fills details. Certify with OTP. No employer approval needed post-exit.
What most guides skip: For EPS under 10 years service, select “Pension Withdrawal” too uses Form 10C. Without it, you lose pension contribution (8.33%). Submit composite claim.
Step 5: Track status. Use “Track Claim Status” with reference number. If pending over 15 days, raise grievance on epfigms.gov.in.
Money credits to bank in 7-20 days post-approval. Delays often from unupdated DOE.
Comparison Table PF Withdrawal Options Side by Side
| Option | Key Feature | Best For | Limitation | Verdict |
| 75% Advance (1 month wait) | Withdraw 75% balance after 1 month unemployed | Need quick cash post-resignation | Leaves 25% locked | Good bridge, but not full access |
| Full Settlement (2 months wait) | 100% PF + interest after 2 months | Complete closure, no new job soon | Longer wait, possible tax | Best for job gap or exit India |
| Transfer to New PF | Move balance to new employer UAN | Job switchers keeping retirement intact | No cash now | Always prefer over withdrawal if rejoining |
Transfer suits most young professionals switching jobs it preserves compound interest. Full withdrawal fits if unemployed longer or leaving workforce. 75% is emergency option only.
Real Benefits With Numbers Where Possible
When you withdraw PF after resignation, you get immediate access to 12% of your salary history plus employer match and 8-8.5% interest.
For a Rs 30,000 monthly salary earner over 2 years, PF balance might hit Rs 8-10 lakhs. 75% gives Rs 6-7.5 lakhs fast covers 6-12 months expenses.
Tax-free if over 5 years service. One overlooked benefit: pension withdrawal via Form 10C returns your EPS share (8.33%), often Rs 50,000-2 lakhs for short service. Most forget this.
Your bank balance jumps, easing job search stress. Interest keeps growing till claim.
Mistakes Most People Make and the Fix
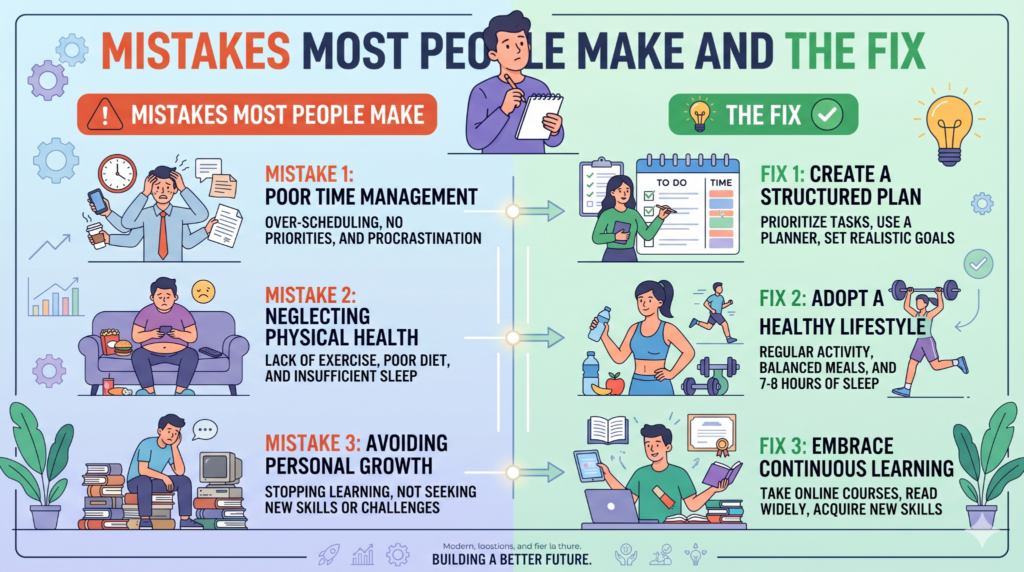
Mistake 1: Filing claim before DOE updates. Happens because excitement overrides check. Claim rejects, wasting time. Fix: Always verify service history first.
Mistake 2: Skipping EPS in composite claim. Young users ignore pension part. Lose thousands forever. Fix: Select both PF final and pension withdrawal.
Mistake 3: Wrong bank details. Old account not linked. Money bounces back. Fix: Update under “Manage Bank” with IFSC, cancelled cheque image.
Mistake 4: Claiming under 1 month. System rejects instantly. Fix: Use passbook app to track exact unemployment days.
Mistake 5: Ignoring tax for <5 years service. TDS 10% over Rs 50k surprises. Fix: Calculate service continuity across jobs via UAN.
Expert Tips That Actually Work
Tip 1: Consolidate old PF first. Multiple accounts? Transfer all to current UAN before claim. Unlocks full amount. Works because EPFO treats as one.
Tip 2: Use Aadhaar e-sign always. Faster approval, no paper. Surprising: even OTP fails less than DSC.
Tip 3: File after exactly 32 days unemployed. Covers notice period glitches. Speeds processing.
Tip 4: Download passbook pre-claim. Proves balance if disputes arise. Many forget post-withdrawal.
Tip 5: Grievance with screenshots. If delayed, upload claim ID + bank proof on epfigms. Resolves 80% cases.
Tip 6: Check PAN link thrice. TDS wrong without it. Tip: Use income tax site verify.
Tip 7: Opt scheme certificate if <10 years EPS. Retains for future pension. Overlooked gem.
Frequently Asked Questions
Can I withdraw PF immediately after resignation?
No, wait 1 month unemployed for 75%, 2 months for full under 2026 rules. Employer DOE must update first. File online then.
PF withdrawal waiting period after resignation?
1 month for partial 75%, 2 months for 100% if no new job. 12 months for remaining 25% in some EPF 3.0 cases.
How to withdraw PF online after resignation?
Login UAN portal, verify KYC, select PF final settlement post-wait, e-sign, track status. 7-15 days processing.
Is PF withdrawal taxable after resignation?
Tax-free over 5 years continuous service. Under 5 years, TDS 10% if >Rs 50,000. Form 15G avoids if income low.
What is Form 19 for PF withdrawal?
Form 19 handles PF final settlement. Part of composite claim with 10C for EPS. Auto-fills online.
PF withdrawal after 1 month unemployment?
Yes, up to 75% balance. Remaining after 2 months or 12. Confirm DOE updated.
How much time for PF amount after claim?
Approval in 7-15 working days, credit same week. Delays if KYC pending.
Can I withdraw PF and EPS together after resignation?
Yes, composite claim covers both. Select pension withdrawal (Form 10C) for <10 years service.
Quick Summary Take This Away
PF withdrawal after resignation needs 1-2 months unemployment wait, active UAN/KYC, and online composite claim. 75% first, full later tax-free over 5 years service. Avoid early filing or skipping EPS.
Transfer if new job soon. Consolidate accounts pre-claim. Track on portal.
Log into your UAN portal today and check DOE + KYC status.
Conclusion
Three takeaways: wait the exact period to avoid rejection, claim PF + EPS together for full money, transfer over withdraw if rejoining soon. Next step: verify UAN details now.
You have the full process. Act on it without worry.