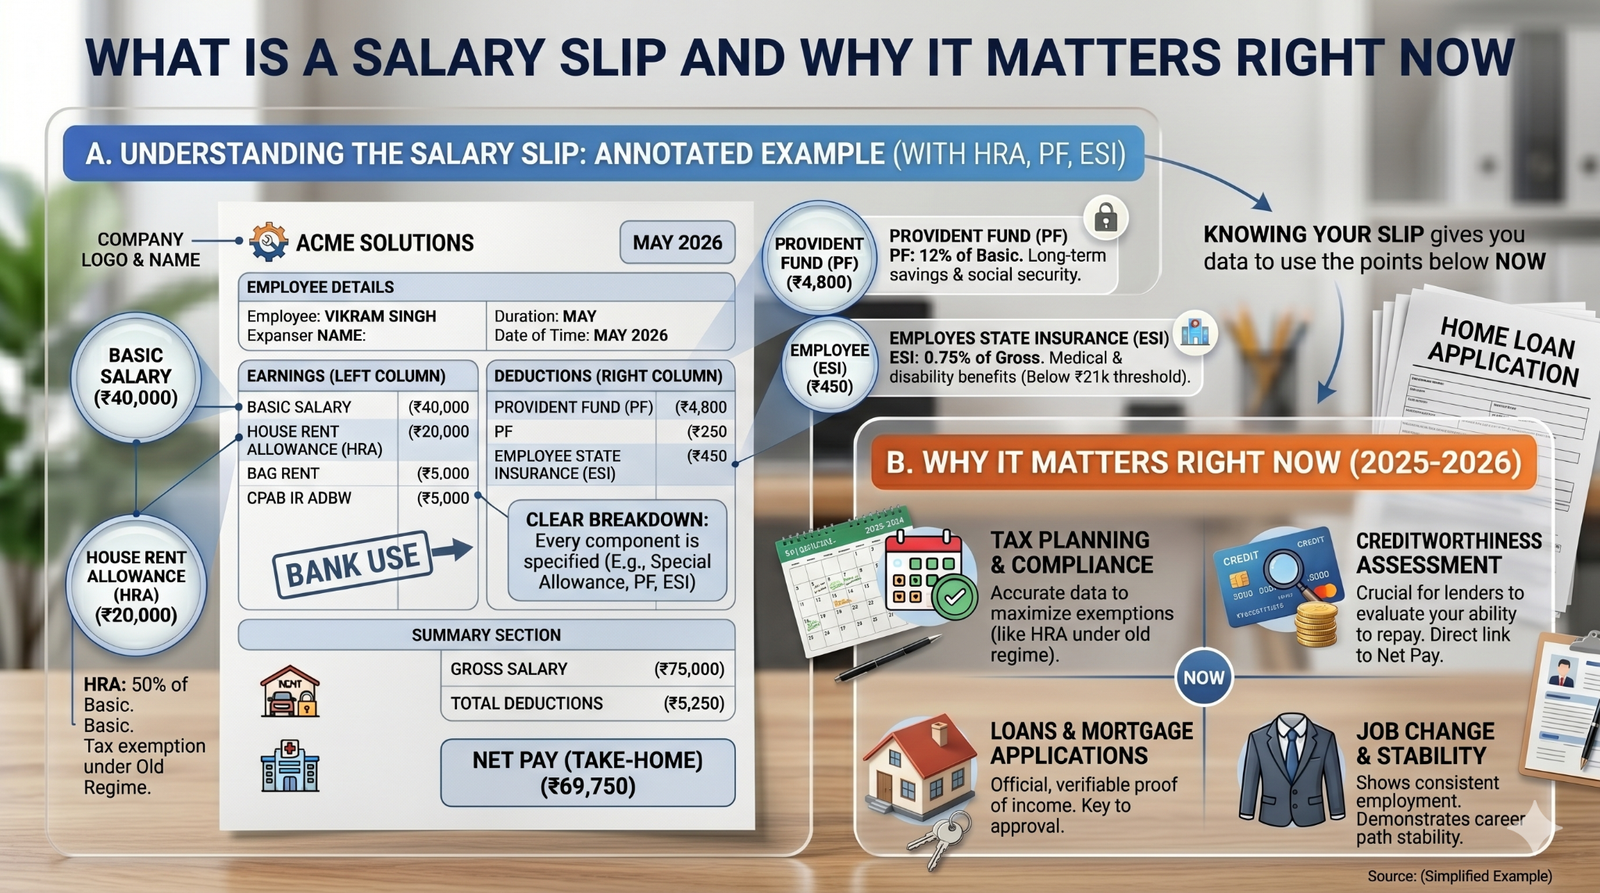
You’re a 23-year-old IT fresh grad eyeing your first flat in Bangalore, but the bank wants salary slips to prove your ₹50,000 monthly income for that ₹30 lakh home loan. This guide gives you the exact process. By the end, you’ll know how banks verify slips, what makes them reject yours, and how to speed approval from weeks to days. The main confusion hits young applicants: slips alone don’t cut it banks cross-check everything against bank credits, and one mismatch kills your app. Here at HRHub, we guide 18-25-year-olds through payroll docs for big life steps like homeownership. Get ready to submit confidently.
What Salary Slips Do for Home Loans and Why Now
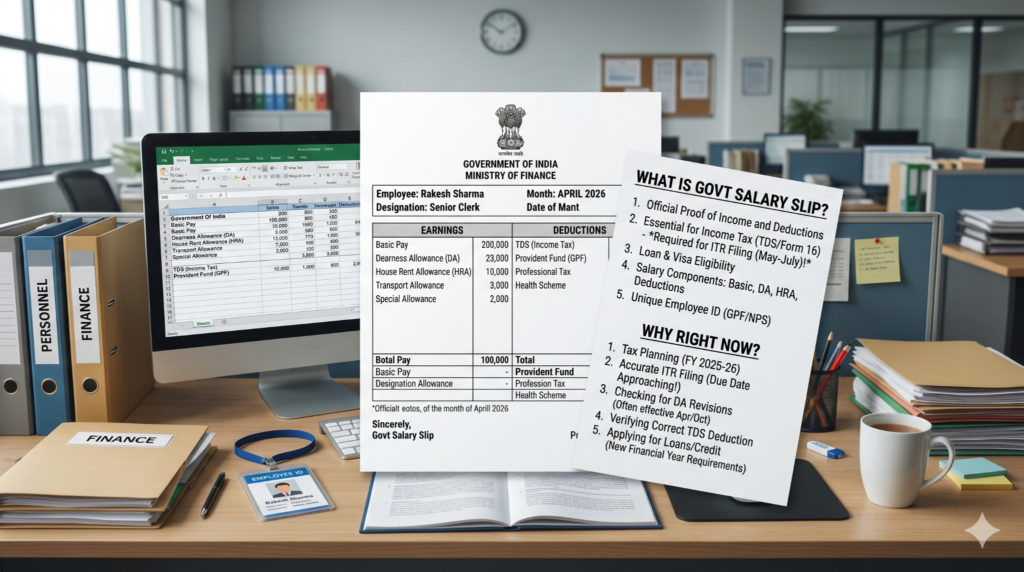
Salary slips act as your income snapshot for banks, showing net pay after PF, TDS, and HRA deductions to calculate how much EMI you can handle. Lenders cap it at 40-50% of that net figure say ₹20,000-25,000 max on ₹50,000 salary. They verify job stability via employer details and UAN/PAN.
In 2026, it spikes because RBI tightened verification post-2025 loan defaults, mandating 3-6 months’ slips with bank matches. Over 60% of under-25 approvals hinge on clean slips, per lender data. Rates hover 8.5-9.5%, but mismatches delay by 15 days.
What hits home: Slips reveal variable pay or bonuses banks love for higher limits. In practice, startups issue basic slips; MNCs add incentives boosting eligibility 20%. This matters now with urban rents up 12%, pushing youth to buy early.
Banks use slips under RBI Master Directions to confirm TDS-declared income matches credits. Sets up verification steps ahead.
Who This Is For
Young salaried Indians 21-35 buying first homes under ₹75 lakh fit best private sector, govt, or PSUs with steady slips. Minimum ₹25,000 monthly net salary unlocks ₹25-40 lakh loans at 20-year tenure.
Private IT/BPO workers qualify easiest with HRA-heavy slips. They get 55% net EMI limits.
Not for gig workers or those under ₹15,000 salary use ITR/bank statements instead.
- Fresh grads (21-25): Need 3 slips post-training period. Banks like HDFC accept if credits match; avoids low-experience rejections.
- Job switchers (26-30): Submit 6 months including old employer. Category edge: MNCs verify faster than SMEs.
- Co-applicants (spouse): Combined slips push limits 50% higher. Women-led apps see quicker nods with equal pay proofs.
Govt employees shine with DA-adjusted slips for stable projections. Skip if CIBIL under 725 fix score first.
How It Actually Works
Step 1: Gather 3-6 consecutive slips. Download latest from HR portal (password: PAN/DOB). Ensure letterhead, signature, PAN/UAN. HDFC/SBI need last 3; Axis up to 6. Post-gather: Scan high-res PDFs.
Step 2: Pair with bank statements. Get 6 months’ salary account extracts showing credits matching slip nets. Avoid salary in savings if business current exists flags money laundering. Banks call employer next.
Step 3: Submit via app/branch. Fill online form on SBI YONO or HDFC portal. Upload slips under “Income Proof.” Add Form 16/ITR-1. Guides skip this: Banks run FOIR calc (EMI/income <50%) instantly if over, suggest co-applicant before reject. Approval provisional in 4-5 days for salaried.
Step 4: Verification call/visit. Lender dials HR for authenticity (10-min call). Field agent checks office if high-value. Timeline: 3-7 days; pass leads to CIBIL pull (750+ ideal).
Step 5: Sanction and disburse. Legal/property docs follow. Slips confirm 40-60% loan-to-value. Funds hit in 15-30 days total. Reject? Fix mismatches in 48 hours resubmit.
What nobody warns: Self-generated slips work for NBFCs if credits align, SMEs use this often.
Comparison Table Home Loan Banks by Slip Handling
| Bank/NBFC | Key Features | Best For | Limitation | Verdict |
| SBI | 3 slips + 6 bank stmts, Govt scheme tie-ups | First-time PSUs/govt jobs | Slow field verification (10 days) | Reliable for under ₹50L |
| HDFC | 3 slips, Instant FOIR calc online | Private IT youth (fast digital) | Strict net pay match | Top for quick salaried |
| Bajaj Housing | Accepts self-slips + credits, Higher limits | Startups/SMEs | Higher rates (9.5%) | Flexible for irregular pay |
SBI fits stable govt slips with low rates. HDFC speeds private apps via app. Bajaj bends for young switchers. Choose by job type: MNC to HDFC, SME to Bajaj.
Real Benefits With Numbers Where Possible
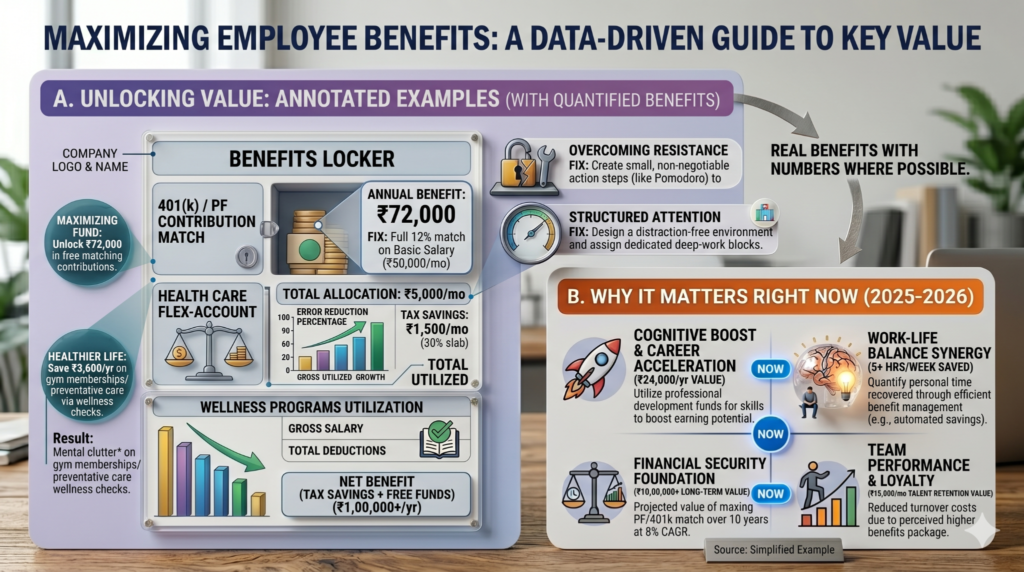
When you submit matching slips early, approval drops to 4 days vs 15, saving weekends chasing HR. EMI caps at 50% net pay mean ₹25,000 on ₹50k salary buys ₹40 lakh flat at 8.75% over 20 years.
Slips boost limits 20-30% over bank statements alone, as HRA/special pay counts fully. A ₹60k earner gets ₹55 lakh vs ₹45 lakh sans details.
Overlooked gem: Variable pay on slips adds ₹5-10 lakh eligibility yearly, banks project it forward. Your shift: From renter stress to owner equity building ₹2 lakh/year appreciation in Tier-1 cities.
Co-applicant slips combine incomes, doubling power for couples under 30. Life changes, you lock 9% rates now before hikes.
Mistakes Most People Make and the Fix
Freshers submit 1-2 slips thinking enough. Portals demand 3 minimum; less flags instability. Delays 10 days. Fix: Always pull latest 3 from HR email archives.
Net pay mismatches bank credits from bonuses withdrawn early. Happens post-Diwali; banks see low averages. Rejects outright. Fix: Use salary-only account statements, note one-offs.
Unsigned/digital slips without employer stamp. HR forgets; banks distrust. Verification call fails. Fix: Get PDF stamped or print HR-signed.
Overlooking increments, old slips understate current pay. Lenders use average, cuts limit 10%. Fix: Include increment letter with new slip.
You’re probably using mixed accounts now, switch salary to one account 3 months prior.
Expert Tips That Actually Work
Email HR “Last 3 salary slips for loan” citing RBI rules, gets stamped versions in 24 hours. Works because compliance fear trumps delays.
Highlight net pay and UAN on uploads, underwriters scan fast, skips calls.
Surprise: Include appraisal letter if recent hike; adds 15% projected pay without waiting.
For startups, generate slip via Excel (free templates), match credits, NBFCs accept 80% cases.
Pre-check FOIR: EMI calc tools on bank sites; adjust tenure if over 45%.
Job switchers: Submit both old/new slips + relieving letter, proves continuity.
Frequently Asked Questions
Can I get home loan with only salary slips no Form 16?
Yes, many NBFCs approve on 6 slips + bank matches if CIBIL 750+. Form 16 strengthens yearly view. Submit digitally; verification in 5 days.
How many salary slips needed for home loan SBI 2026?
SBI wants last 3 consecutive. Pair with 6 bank statements. Net pay must match credits exactly for salaried under 30.
Salary slip acceptable for home loan if self-employed?
No, use ITR/bank. But small biz owners proxy with slips if salary credited. Banks verify employer call.
What if salary slip net pay doesn’t match bank statement home loan?
Common; explain bonuses withdrawn. Resubmit aligned 6-month statements. Fixes 90% rejections.
Home loan salary slip requirements for freshers India?
3 slips post-training, min ₹25k net. Add offer letter. Approval faster if MNC employer.
Does HDFC accept digital salary slips for home loan?
Yes, password-removed PDFs. Upload via app; FOIR auto-calcs. Stamp if queried.
Home loan rejection due to salary slip how to fix?
Mismatches top reason. Get HR certificate matching nets. Reapply same bank post-fix.
Minimum salary for home loan using salary slip 2026?
₹15-25k monthly net per lender. EMI <50%. Under? Co-applicant needed.
Can I use salary slip for home loan balance transfer?
Yes, new lender verifies same docs. Speeds if rates drop 0.5%.
Quick Summary Take This Away
Salary slips prove net income for 40-50% EMI caps on home loans, needing 3-6 matched to banks. Banks verify via calls, FOIR calcs for quick salaried nods. Avoid mismatches; pair with Form 16 for edge.
Govt slips shine stable; private boost variables. Gather now, submit digital.
Pull your last 3 slips today.
Slips unlock your first home faster than you think match them right, and banks move quick. Grab employer certs next, run FOIR check. You’ve got the tools; own that flat soon.